Helping Mortgage Lenders Make Better Decisions Since 1946

Helping Mortgage Lenders Make Better Decisions Since 1946


One Mission. Eight Decades of Progress.
When Informative Research opened its doors in 1946, the mortgage lending process looked nothing like it does today. Borrower information lived in handwritten or typewritten documents, making it difficult to access, share and verify. Lenders verified borrower income and employment through standardized verification forms exchanged via the U.S. Postal Service. A national credit bureau, much less a standardized credit score, was nonexistent, and property appraisals depended on an individual appraiser’s judgment. From start to finish, the entire mortgage origination process could take up to eight weeks.

Founded as a research services company serving the mortgage and insurance industries, IR helped lenders navigate that paper-driven world by gathering and delivering the information they needed to make lending decisions. When the Buckner family acquired IR in 1973, they expanded the company’s mission by transforming it into the technology-driven partner lenders know today. As mortgage lending progressed from paper records to credit scoring, automated underwriting and digital verification, IR evolved alongside it, continually developing new ways to help lenders work faster and make more informed decisions.

Evolving with the Industry

The industry’s transformation took off in 1989 with the introduction of the first standardized FICO® credit scoring model, marking the start of a more objective approach to credit risk. By the mid-1990s, Fannie Mae and Freddie Mac had cemented national standards for credit scoring.

Against that backdrop, IR introduced many of the tools that shaped modern mortgage lending to the broader market. In the 1980s, the company helped pioneer the merged credit report, delivering to lenders a unified view of borrower credit across bureaus. When Fannie Mae launched Desktop Underwriter® (DU®), IR was among the earliest credit reporting agencies integrated into the platform. In 2016, IR became one of the first to introduce a CRA-delivered soft inquiry prequalification report, giving lenders a smarter, borrower-friendly way to qualify prospects before a hard pull was ever needed. Most recently, IR was an early provider of VantageScore® 4.0, giving lenders access to additional scoring models.

Each milestone reflects the same commitment: help lenders make better decisions by making trusted information easier to access.

Innovation at Work Today

IR continues building tools that simplify mortgage lending and help lenders access trusted information faster. One example is AccountChek®, which lenders have relied on for years to validate borrowers’ assets, income and employment and support eligibility for rep and warrant relief through the GSEs’ data validation initiatives. This year, IR rebuilt the platform to improve verification speed, simplify administration and strengthen operational resilience. AccountChek is now also unified with the IR Verification Platform, bringing all of IR’s verification solutions together into a single user experience.

IR also introduced Action Center to eliminate one of the most common sources of operational friction. It’s a self-service portal accessible directly from the credit report PDF, letting underwriters and processors handle common credit report tasks (e.g., resetting duplicate flags, correcting borrower demographics, swapping borrower positions, ordering supplements, generating consumer copies, etc.) without picking up the phone. Each user sees only the actions available for their role, creating a cleaner experience and reducing clicks.

These latest advancements build on a broader portfolio of solutions that help lenders work more efficiently. Lenders rely on the IR Credit Platform to manage costs and reduce unnecessary credit pulls, while IR Risk Solutions help identify fraud, minimize processing delays and support compliance.

Building Toward What’s Next

The mortgage industry has changed dramatically since 1946, and the pace of change continues to accelerate. True to its mission, IR is building the next generation of tools to help lenders navigate that complexity.

Today’s lenders have access to more data than ever, yet it remains scattered across independent systems, with manual workflows filling the gaps. Rather than asking lenders to move between disconnected systems, IR is working to bring credit, verification, fraud detection and compliance data together within the workflows lenders already use. That means continued investment in unified platform infrastructure, modern APIs, automation-ready workflows and flexible delivery models that let lenders choose tools that fit their business.

For 80 years, Informative Research has helped lenders find, verify and use the information they need to make confident lending decisions. The technology has changed. The mission hasn’t.

More Company News

Helping Mortgage Lenders Make Better Decisions Since 1946

Helping Mortgage Lenders Make Better Decisions Since 1946

One Mission. Eight Decades of Progress.
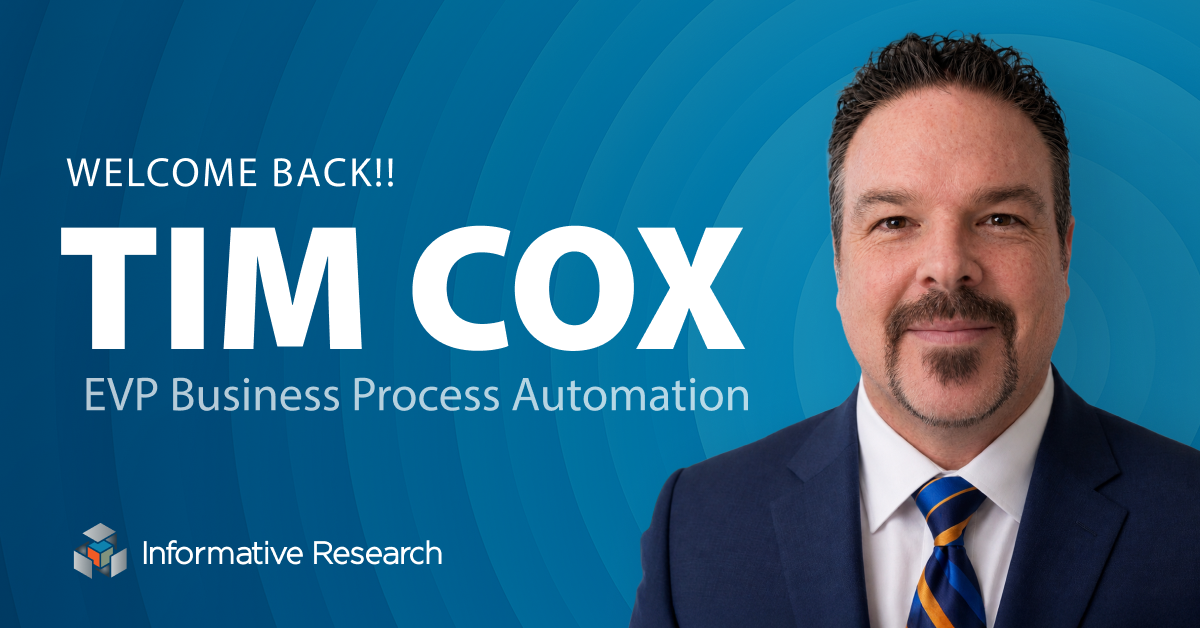
Tim Cox Returns to Lead Business Process Automation at IR

Tim Cox Returns to Lead Business Process Automation at IR

GARDEN GROVE, Calif., Sep. 17, 2026 —Informative Research(IR), a leading technology provider of data-driven credit and verification solutions for the...